
Some homeowners are finding out what their insurance doesn’t cover after a severe storm in southern Ontario. CTV’s Colton Wiens reports.
Doug and Alicja Arnold say Wednesday’s storm didn’t just damage their home; it also started a struggle with their insurance provider.
A tree on the Kitchener couple’s property broke in half and fell onto the roof of their house.
“Nobody ever expects that you’re going to be the next victim,” said Doug. “Unfortunately, this time we were. I don’t know why the rest of the neighborhood doesn’t have what we have.”
They quickly contacted their insurance company.
The response wasn’t what the Arnolds expected.
“I’m learning a lot and also very disappointed,” Doug admitted.
Their insurer informed them they would only cover part of the cost to remove the tree and fix the roof. The Arnolds mentioned they checked their policy but couldn’t find that section.
“Generally, I’m very, very upset,” said Alicja. “I’m thinking, if I’ve been paying regular insurance for 25 years, how long I’ve been living in this house, they’re supposed to be covering everything.”
Issues with the Tree
The tree itself is what’s complicating things.
Their insurer is willing to pay for the part that fell on the roof. But the Arnolds said they were told that both halves needed removal because one was dangerous, which isn’t covered by their policy.
This means they’ll have to pay out of pocket.
“If half the tree is standing and half the tree is on the house, what good is a half-tree standing?” Doug asked. “They’re still part of one piece; they should compensate for each other.”
Charnwood Court kitchener storm A tree split in two on Charnwood Court in Kitchener during a storm on Sept. 3, 2026. (Rowen Fisler/)
Understanding Policy Details
According to the Insurance Bureau of Canada (IBC), most policies mainly cover damage to homes.
“A lot depends on specifics,” explained Amanda Dean, vice-president for Ontario and Atlantic at IBC.
While she didn’t know about the Arnolds’ situation specifically, she shared some insights into how insurers make decisions.
“The first detail to consider is what kind of home insurance policy we’re discussing? Some people have what we call a ‘no-frills insurance policy.’ Those are usually when upgrades are necessary but offer coverage people can obtain,” she noted. “Now, if we’re looking at standard home insurance policies-so if your home meets today’s building codes including roofs and heating systems-the damaged part of any tree would certainly be removed.”
There are also additional factors involved.
“When it comes to trees and shrubs, there are limits within policies,” Dean clarified. “Primarily, home insurance covers structures-buildings-and certainly contents as well.”
The Arnolds mentioned that only part of the tree seems to have punctured the garage roof and not affected the main area of their house.
Two days after the storm hit , the tree remained where it had fallen. But they’re concerned that any damage might worsen over time. p >
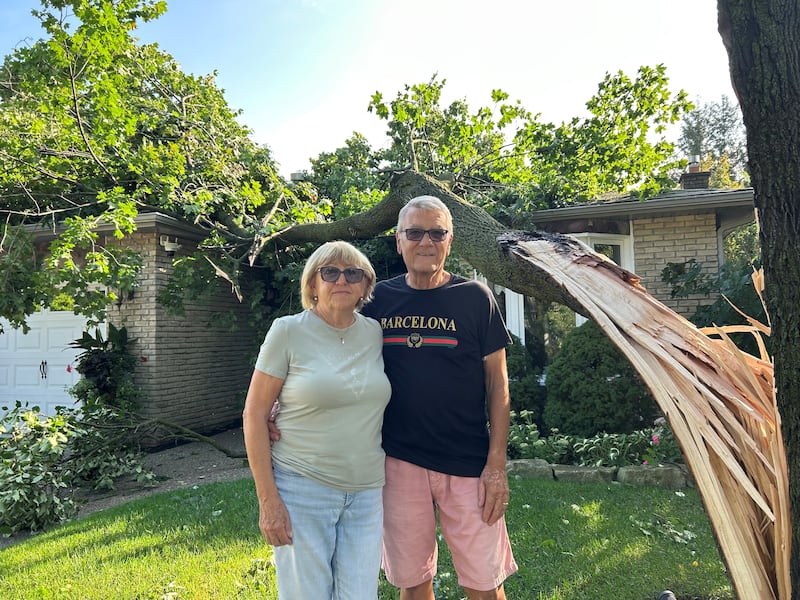 Charnwood Court in Kitchener storm sept 2 tree damage Alicja Arnold (left) and Douglas Arnold (right) in front of their tree which was damaged during a storm on Sept 2nd 2026 at Charnwood Court located within Kitchener.(Rowen Fisler/)Dean offered one final tip.” Be sure you understand your policy details ,” she advised.” Also don’t hesitate asking questions from your adjuster regarding any confusion.”


